Summary:
If you’re thinking about a pawn loan and you want to know what it’s actually going to cost — you’re asking the right question. Most people walk in without a clear sense of the rate, the fees, or the timeline, and that’s where things get murky. The good news is that New York State has some of the clearest, most consumer-friendly pawn laws in the country. The rate is capped by law, the fees must be disclosed upfront, and your rights as a borrower are spelled out in writing before you sign anything. Here’s what all of that looks like in practice — and what it means for Nassau County residents specifically.
Pawn Shop Interest Rates: New York State Legal Requirements
New York State caps pawn shop interest at 4% per month under Article 5 of the General Business Law, which governs all licensed collateral loan brokers — the legal term for pawnbrokers — operating in the state. Annualized, that’s 48% APR. It applies uniformly across Nassau County and throughout the state, which means the rate at our shop is the same as any licensed operation in Manhattan or Suffolk County. The law levels the playing field on cost, so what actually differentiates one shop from another is expertise, loan value, and how we treat you.
To put that in perspective: some states allow pawn shops to charge as much as 20% per month, which works out to 240% APR. New York’s 48% cap is among the lowest in the country. For a loan held for one month, the maximum allowable rate serves as a strict legal ceiling, not a suggestion.
How to Calculate the Total Cost of a Pawn Loan in Nassau County
The math is straightforward once you know the formula. Your total repayment is the original loan amount plus the monthly interest charge multiplied by the number of months you hold the loan. As the term extends from one to two months, that monthly percentage accumulates accordingly. If you hold the loan for four months, the standard loan term in New York, the full term of monthly interest charges applies to your final repayment amount.
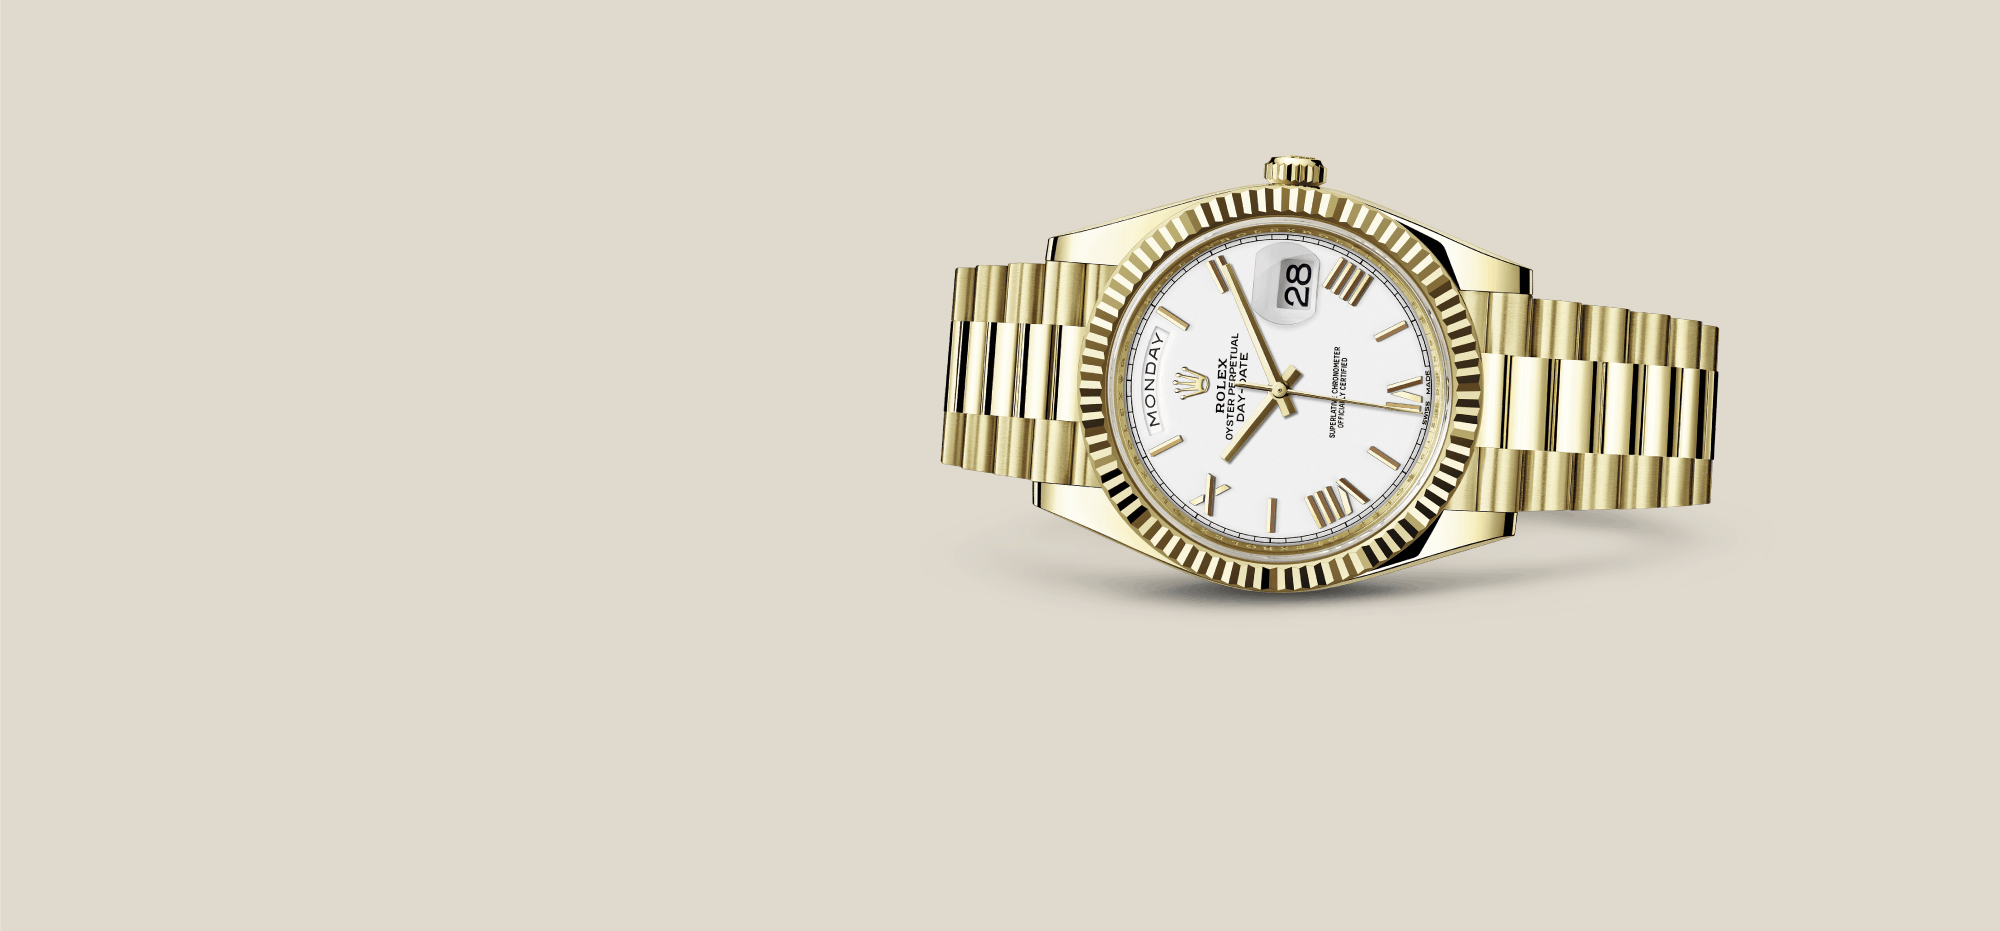
For higher-value items, the numbers scale the same way. If you bring in a luxury watch like a Rolex to secure a loan, the interest accrues at the legal monthly rate for each month you hold the loan. Over the full four-month term, those accumulated monthly charges apply directly toward the total required to retrieve your watch. That final amount is completely transparent from the start, and you will have it documented in writing on your pawn ticket before you agree to anything.
This is worth emphasizing because a lot of people conflate the monthly rate with the APR, or assume there are additional costs layered on top that inflate the real number. In New York, the pawn ticket is a legal document. It must state the loan amount, the interest rate, the total interest due, and the total repayment amount before you sign. Any fee that isn’t on that ticket isn’t legal. There’s no mechanism for a licensed pawnbroker in this state to add charges after the fact — the law doesn’t allow it.
One thing to keep in mind when comparing pawn loans to other borrowing options: personal loan APRs currently average around 12% nationally, which is lower than 48%. But personal loans require a credit check, income verification, and approval — and they show up on your credit report. A pawn loan requires none of that. For Nassau County residents who are protecting a strong credit profile for a mortgage application or a business line of credit, the privacy of a pawn loan has real value that a raw APR comparison doesn’t capture.
Why Nassau County Borrowers Often Get More Than They Expect
The rate cap is the same everywhere in New York, but the loan amount you’re offered isn’t. That depends entirely on how well we understand the resale value of what you’re bringing in — and that’s where specialization matters.
A general pawn shop appraising a Rolex Submariner may offer a conservative number because they’re not confident in the secondary market value. We actively buy, sell, and service luxury watches, maintaining an extensive pre-owned Rolex inventory, so we have a much clearer sense of what that watch is worth on the open market today. That knowledge translates directly into a higher loan offer. We offer up to 70% of item value on collateral loans, which is meaningfully above the industry norm of 25% to 60% of resale value.
For Nassau County residents, this matters more than it might in other markets. The North Shore communities — Great Neck, Manhasset, Roslyn, Oyster Bay — have a high concentration of fine jewelry, estate pieces, inherited watches, and luxury accessories that have been sitting in a drawer for years. A lot of people in those communities have never considered a pawn loan because they assumed the offer would be insulting. The reality is that a shop with the right expertise can appraise a piece accurately and make an offer that actually reflects what it’s worth. That changes the calculation entirely.
Nassau County’s median household income ranks among the highest of any county in New York State, but strong earnings do not insulate anyone from a cash-flow crunch. Local property tax obligations are among the steepest in the country, and sudden medical needs, home repairs, private school tuition, or commercial expenses can impact residents across all income brackets. A collateral loan secured by an asset you already own provides a fast, private way to bridge that gap without tapping into retirement accounts or adding inquiries to your credit profile.
Pawn Shop Fees in New York: What the Law Requires Shops to Disclose
The 4% monthly rate is the interest charge — but consumers often wonder whether there are additional fees stacked on top of it. In New York, the answer is that everything must appear on the pawn ticket before the transaction is completed. Storage fees, appraisal fees, any other charge — if it’s not itemized on that ticket, it’s not enforceable and it’s not legal for a licensed shop to collect it.
This is a meaningful consumer protection that most people don’t know about. The pawn ticket isn’t just a receipt — it’s a legally required disclosure document, and New York’s Truth in Lending Act compliance requirements mean the total cost of your loan has to be spelled out clearly before you agree to anything. If a shop is reluctant to show you the ticket before you hand over your item, that’s a problem worth paying attention to.
Pawn Loan Terms in NY: Grace Periods, Extensions, and Redemption
The standard pawn loan term in New York is four months — 120 days. During that window, your item is held in secure storage and you can redeem it at any time by repaying the loan amount plus the interest accrued to that point. You don’t have to wait until the end of the term. If you want your item back in three weeks, you pay three weeks’ worth of interest and you’re done.
If the 120-day deadline is approaching and you’re not ready to repay, you have options. You can extend the loan by paying the interest that’s accrued — essentially resetting the clock without losing your item. This isn’t a penalty or a special arrangement; it’s a standard part of how pawn loans work in New York, and we can walk you through it clearly.
What happens if you don’t repay and don’t extend? We take ownership of the item. That’s the full extent of the consequence. There are no debt collectors. No calls. No legal action. No entry on your credit report. The loan is non-recourse, which means the collateral is the only thing at stake — not your credit score, not your bank account, not your financial history. For people who are nervous about what happens in a worst-case scenario, that’s an important thing to understand before they walk in.
It’s also worth knowing that New York law gives you a 5-business-day cancellation window on pawn sales, and if you’ve sold a piece of jewelry, a watch, precious metals, or coins, you have 14 days to convert that sale to a collateral loan instead. These protections exist specifically to give borrowers room to reconsider — and they’re not widely advertised, but they apply to every licensed transaction in the state.
New York Pawn Laws: Licensing, Bonding, and What Makes a Shop Legitimate
Not every shop offering cash for valuables operates under the same legal framework. In New York, a licensed collateral loan broker, the formal term for a pawnbroker, must obtain a license from local authorities, register with the New York State Comptroller, and secure a surety bond to guarantee faithful performance of their duties. Licensed pawnbrokers are also required to maintain complete transaction records open to police inspection and submit daily reports to law enforcement detailing all items received. This reporting protocol exists to prevent stolen property from circulating and to protect both consumers and the broader community.
For Nassau County residents, this matters because the licensing framework creates accountability that unlicensed buyers — online resellers, informal gold buyers, pop-up “we buy gold” operations — simply don’t have. When you bring a Rolex or a diamond ring to a licensed pawnbroker, there’s a legal paper trail, a bonded obligation, and a regulatory body that can pull their license if they don’t follow the rules. That’s a very different situation from shipping your watch to a stranger on the internet.
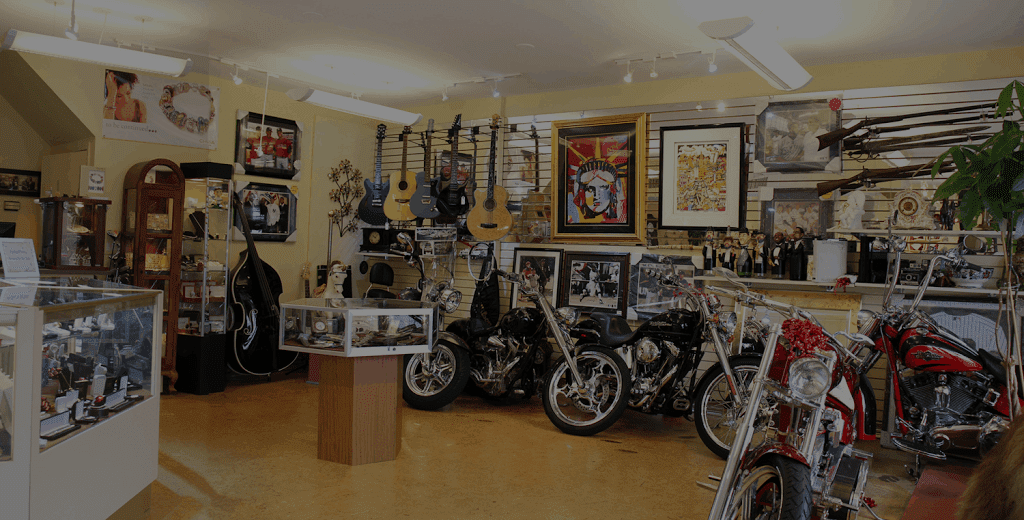
We’re voted the Best Pawn Shop on Long Island by the Long Island Press — and we’re also an Authorized Ball Watch Dealer, which is a formal brand authorization that requires meeting standards most pawn operations can’t satisfy. These aren’t marketing claims; they’re verifiable credentials that reflect how we operate. Nassau County residents from Syosset to Massapequa, from Hicksville to Long Beach, make the drive to our Huntington location on Jericho Turnpike because they want a shop that knows what it’s doing with high-value items — and can prove it. The licensing and bonding are the floor. The expertise is what’s built on top of it.
One more thing worth mentioning: licensed NY pawnbrokers are required to hold your pledged item for the full loan period before we can sell it. We cannot sell your Rolex on day 60 of a 120-day loan. The law prohibits it, and violating that rule puts our license at risk. Your item is not going anywhere until the redemption window has fully closed — and even then, you’ll receive notice before any sale takes place.
What Nassau County Borrowers Should Know Before Taking a Pawn Loan
New York’s pawn laws are genuinely consumer-friendly — the rate cap, the disclosure requirements, the non-recourse structure, the cancellation window. Most people who hesitate before using a pawn loan do so because they don’t know any of this. Once you understand that the rate is capped at 4% per month, that every fee must be on the ticket before you sign, and that the worst-case scenario is simply forfeiting your collateral with no credit impact, the decision looks a lot different.
The other piece is knowing where to go. The loan value you’re offered depends entirely on how well we understand what you’re bringing in. For Nassau County residents with fine jewelry, luxury watches, gold, or estate pieces, that expertise gap can mean thousands of dollars of difference in what you walk out with.
If you have questions about a specific item or want to understand what a loan might look like before you commit to anything, Gold Coast Jewelry & Pawn is a short drive from the Nassau County line on Jericho Turnpike — and there’s no obligation to accept an offer. Come in, get an appraisal, and make an informed decision.