Summary:
Most people don’t start researching loans because things are going well. A car breaks down. A tax bill lands early. A medical expense shows up without warning. Whatever the reason, the clock is already running — and the last thing you need is a process that takes five business days just to tell you whether you qualify.
This page is for anyone in Nassau County who’s weighing their options and wants a straight answer. We’ll walk you through how collateral loans actually work, how they compare to bank loans on speed and credit requirements, and when each one makes more sense. No fluff, no pressure — just the information you need to decide.
How Secured Loans and Collateral Loans Actually Work
Both collateral loans and bank loans are forms of secured lending — but they work very differently in practice. A bank secured loan ties your creditworthiness to an asset, like your home or car, and still requires a full underwriting process: credit check, income verification, tax documents, debt-to-income review. The asset is a backstop, not a shortcut.
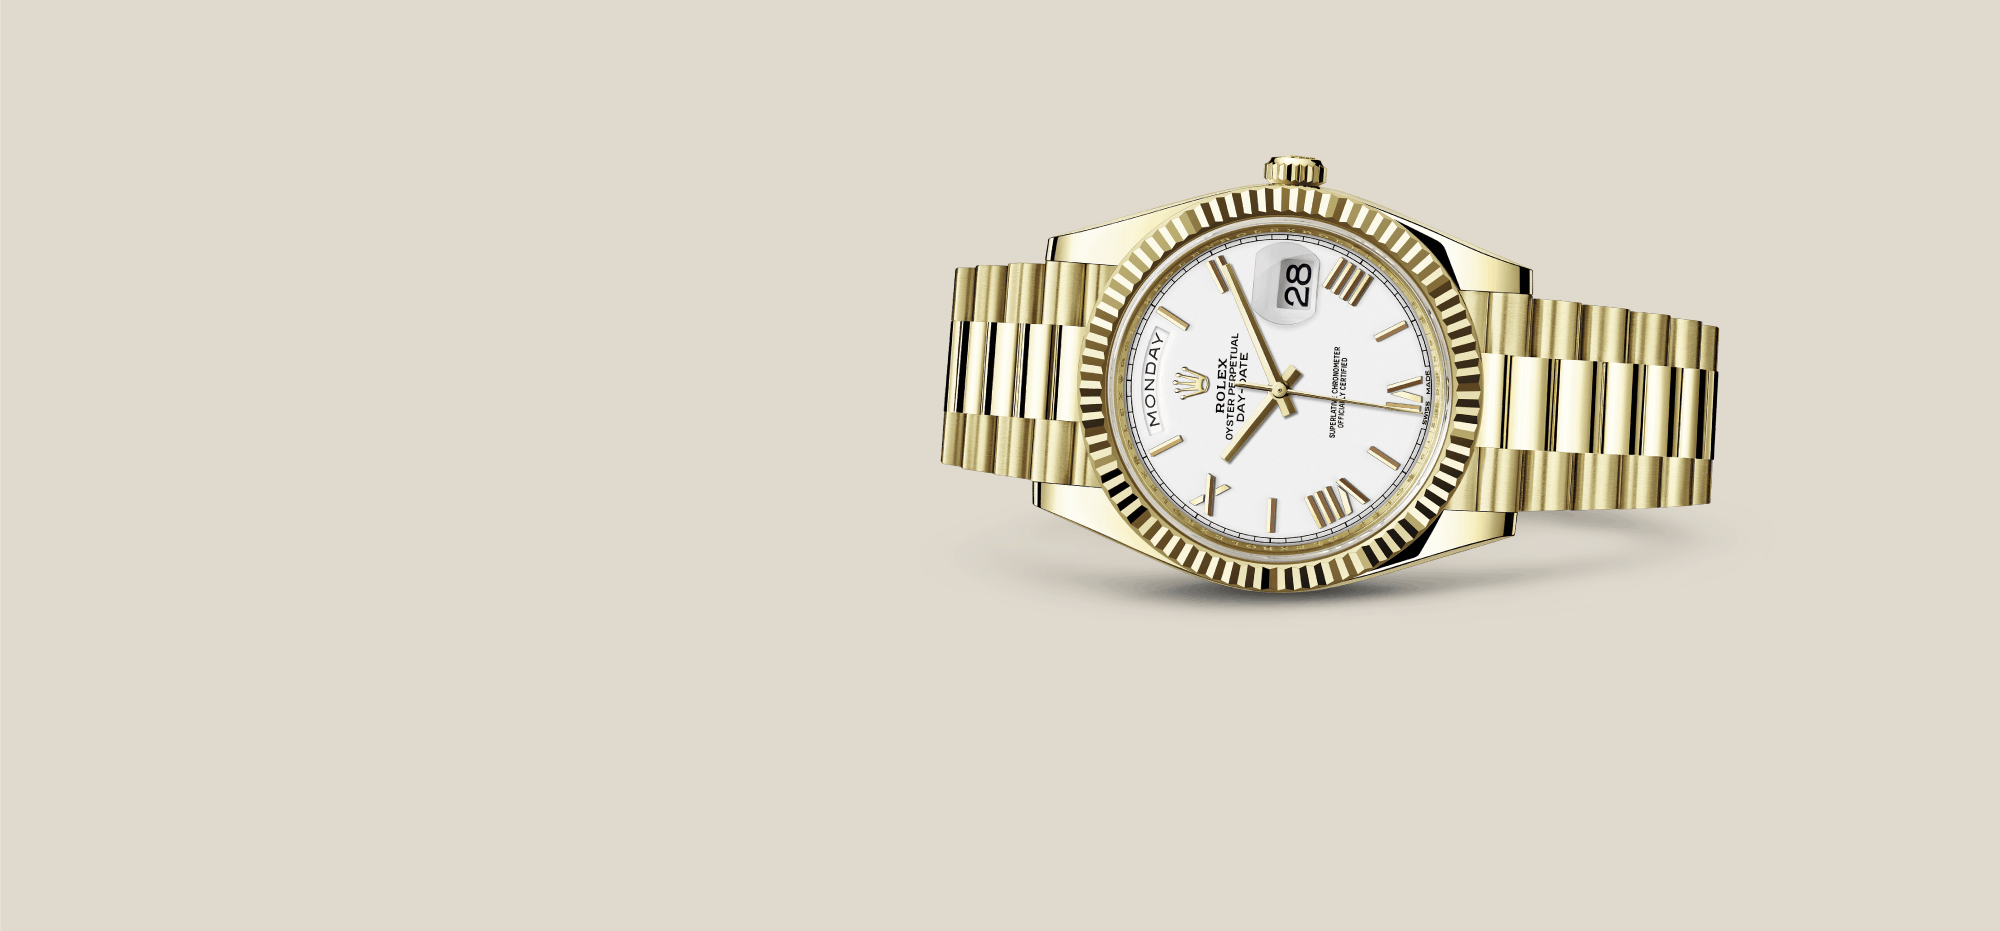
A collateral loan from us flips that model. The item you bring in — a Rolex, a diamond ring, a gold chain — is the entire basis for the loan. Your income, your credit score, your employment history — none of it factors in. The value of what you’re holding determines what you can borrow, and the whole process happens in person, in real time.
That’s the core difference. One relies on who you are financially. The other relies on what you own.
No Credit Check Loans: Why Pawn Loans Don't Need Your Credit History
When a bank looks at your loan application, they’re essentially asking: “Based on your financial past, how likely are you to pay this back?” That’s a reasonable question — for them. But it means people who’ve had a rough stretch, never built credit, or simply don’t want another hard inquiry on their report are often left without options.
Pawn loans work from a completely different starting point. The question isn’t whether you’ll repay — it’s whether the item you’re bringing in has enough resale value to cover the loan if you don’t. Because we hold your item as security, your credit score is irrelevant to the transaction. There’s no application to fill out, no bureau to pull from, and no inquiry that shows up on your report afterward.
That last part matters more than people realize. Whether you repay the loan or not, your credit score is untouched. Pawn loans are not reported to any credit bureau. This is fundamentally different from bank loans, online lenders, and even most credit union products — all of which report payment history and can damage your score if things go sideways.
For Nassau County residents who’ve been turned down before, or who simply don’t want a bank digging into your finances for a short-term need, this is a meaningful distinction. You walk in with a valid ID and the item you want to use as collateral. That’s the entire application process.
One thing worth understanding: the loan amount you’re offered is based on the item’s resale value, not what you paid for it or what it’s insured for. We’ll explain that clearly upfront. We offer up to 70% of an item’s value on collateral loans — which is above the industry average of 25 to 60 percent. On a $5,000 watch, that difference in percentage points translates to real money in your hand.
How Long Does It Actually Take to Get Cash From Each Loan Type?
Speed is where the gap between collateral loans and bank loans becomes impossible to ignore. A traditional bank personal loan — even from an institution you’ve banked with for years — typically takes several business days from application to funding. You submit documentation, wait for underwriting, wait for approval, then wait again for the funds to actually land. Online lenders can move faster, but “24 to 48 hours” is still a day or two you may not have, and they still run credit checks and require income verification.
A pawn loan can put cash in your hand in under an hour. You bring in your item, it gets appraised in front of you, you review the terms, and if you agree, you walk out with money. No waiting period. No follow-up call from an underwriter. No second appointment.
For Nassau County homeowners facing a bi-annual property tax installment — and those bills regularly run $5,000 to $15,000 per payment — the difference between same-day cash and a week-long bank process is not abstract. It’s the difference between paying on time and paying late fees. The same applies to anyone dealing with an unexpected car repair, a medical bill, or a rent shortfall that doesn’t care what day of the week it is.
It’s also worth understanding what you’re agreeing to when you take a pawn loan. You receive a written pawn ticket that details the item description, loan amount, interest rate, and repayment deadline. New York State law requires this documentation — pawnbrokers operating here are licensed as collateral loan brokers under General Business Law §52 and must comply with the federal Truth-in-Lending Act. The terms are disclosed in writing before you agree to anything.
And if you can’t repay? We keep the item. That’s it. No debt collectors. No legal action. No credit damage. The transaction ends cleanly. The National Pawnbrokers Association reports that roughly 85% of pawn loans are repaid and items are retrieved — but knowing the exit is clean if you need it removes a lot of the anxiety around the decision.
Fast Cash Loans in Nassau County: Comparing Real Costs, Not Just Rates
Interest rate comparisons between pawn loans and bank loans often get distorted by APR math. APR is designed to compare loans over a full year — and when you apply it to a 30-day pawn loan, the annualized number looks alarming even if the actual dollar cost is modest. A $500 pawn loan with a $20 fee repaid in 30 days costs you $20. That’s the real number.
Compare that to a payday loan on the same amount — fees of $75 to $150 are common, with APRs regularly running 300 to 400 percent. Or a credit card cash advance, which charges a 3 to 5 percent upfront fee plus interest that starts accruing immediately, with no grace period. For short-term, small-dollar needs, pawn loans are often the most cost-effective option outside of borrowing from family.
What Happens to Your Collateral While the Loan Is Open?
This is the question most people don’t ask out loud but are absolutely thinking about. If you pawn your grandmother’s ring or a watch you’ve worn for fifteen years, what actually happens to it while the loan is active?
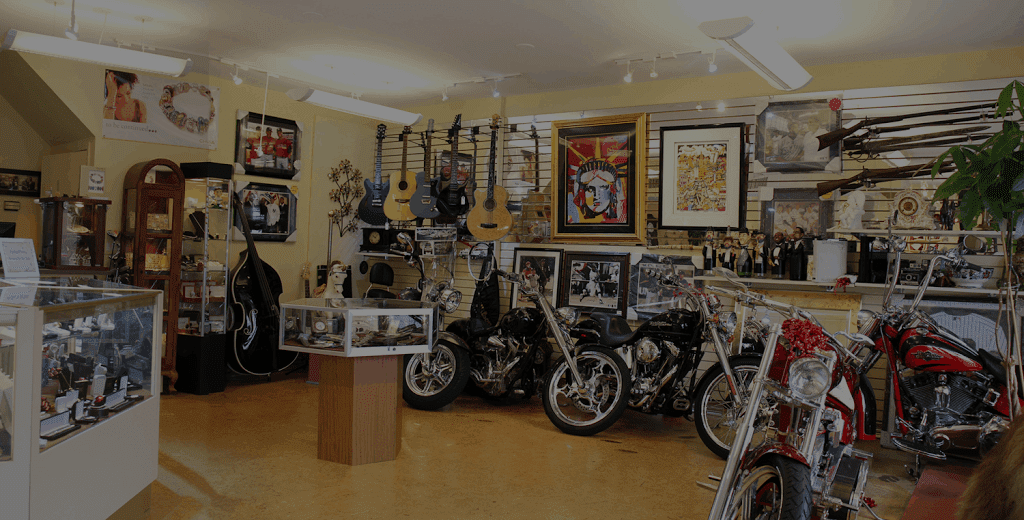
At our shop, your item is stored securely on-site for the entire loan period. It doesn’t get sold, displayed, or moved — it waits for you. When you come back to repay the loan, you get the item back in the same condition it was in when you left it. The pawn ticket you receive at the time of the loan is your legal claim to that item.
During the appraisal itself, your item shouldn’t leave your sight. We walk you through the process in front of you — explaining what we’re looking at, why, and what that means for the loan offer. If something about the process feels rushed or opaque, that’s a signal worth paying attention to.
We’ve operated on East Jericho Turnpike in Huntington since 2010 — 15 years at the same location, with the same staff, serving Nassau County and the surrounding communities. Customers along the Route 25 corridor — from Syosset and Woodbury in Nassau County through Huntington Station and beyond — have come to know what to expect here. Named staff members appear in reviews across multiple platforms over multiple years, which tells you something about the consistency of the experience.
We’re also an Authorized Ball Watch Dealer and a recognized Rolex specialist. That level of expertise matters when you’re bringing in a luxury watch for appraisal. We’re not guessing at value — we know the market for these items the way a jeweler knows their inventory, because we operate on both sides of it every day.
When Does a Collateral Loan Make More Sense Than a Bank Loan?
There’s no universal answer here, and anyone who tells you pawn loans are always better — or always worse — than bank loans isn’t being straight with you. The right choice depends on what you need, how fast you need it, and what resources you have available.
A bank loan makes more sense when you need a large sum, have time to wait for approval, and qualify for a competitive interest rate. If you’re financing a home renovation or consolidating significant debt and your credit is in good shape, a bank loan will almost certainly cost you less over the life of the loan.
A collateral loan makes more sense when speed matters, when the amount you need is relatively modest, or when a credit check isn’t something you want to deal with. It’s also the right tool when you want to preserve liquidity without selling an asset permanently. Pawning a watch to cover a short-term gap is not the same as selling it — you’re borrowing against it, and you get it back when you repay.
For Nassau County residents specifically, there’s a pattern worth naming. The cost of living here is high — property taxes, LIRR commuting costs, and housing expenses can put real pressure on household cash flow even for people earning well above the state median. That pressure doesn’t always align with bank timelines or credit eligibility. A collateral loan against a piece of jewelry or a luxury watch can bridge a gap quickly and privately, without triggering a credit inquiry or requiring you to explain your finances to anyone.
It’s also worth knowing that the communities along Long Island’s North Shore — the area we take our name from — have historically had high concentrations of luxury goods ownership. Rolex watches, fine jewelry, and estate pieces are common in households from Great Neck to Oyster Bay. If you own items like these and find yourself needing short-term liquidity, you may have more borrowing power sitting in your jewelry box than you realize. We offer up to 70% of item value on collateral loans, and we’ll tell you exactly what that number is before you commit to anything.
Collateral Loans vs Bank Loans: Which One Is Right for Your Situation?
If you need cash today and you own something of value, a collateral loan gives you a path that no bank can match on speed — and one that doesn’t touch your credit or require a stack of paperwork. If you have time, strong credit, and a larger borrowing need, a bank loan may be the better long-term fit. Both have a place. Knowing which one fits your situation is what matters.
For Nassau County residents who want to explore what a collateral loan could look like for them, we’re a short drive up Jericho Turnpike. We’ve been doing this for 15 years, we’ve been voted the Best Pawn Shop on Long Island by the Long Island Press, and we’ll give you a straight answer on what your item is worth — no pressure, no obligation.
Come in, bring what you’ve got, and see what your options actually are.